

Intel presents good financial data, but 10nm and AMD EPYC begin to weigh down


Intel's revenue is presented, which is slightly lower than expected, due to the 10nm ballast and the arrival of AMD EPYC processors.
Despite the bad moments of Intel regarding the development and manufacture of 10nm processors, which do not come due to the problems that the company has encountered with regard to lithography. The advent of AMD EPYC processors has also been a major problem in the data center business. These events are taking a toll on the company's financial data, which despite being really good, are hampered by the two events.
Good income from Intel, but the non-arrival of 10nm and AMD EPYC make a dent.
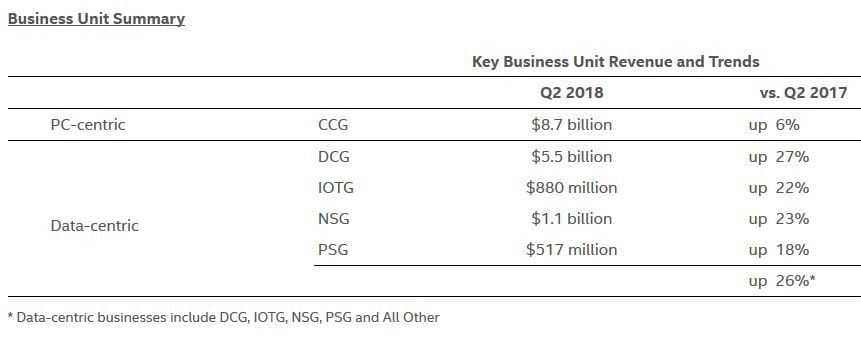
Intel's sales of data center products for web and mobile application development increased 26.9% to 5.550 billion in the company's second quarter. An additional $ 100 million in revenue was expected, but the expectation was narrowly missed. This is because AMD with EPYC has cut back a bit.
Bob Swn, the company's interim president after the Bryan Karzanich scandal, who has said that 10nm lithography-based processors will hit the market during the second half of 2019. Murthy Renduchintala, who is chief of chip architecture at the company, who has said that 10nm processors will arrive for data centers shortly after the mainstream market.
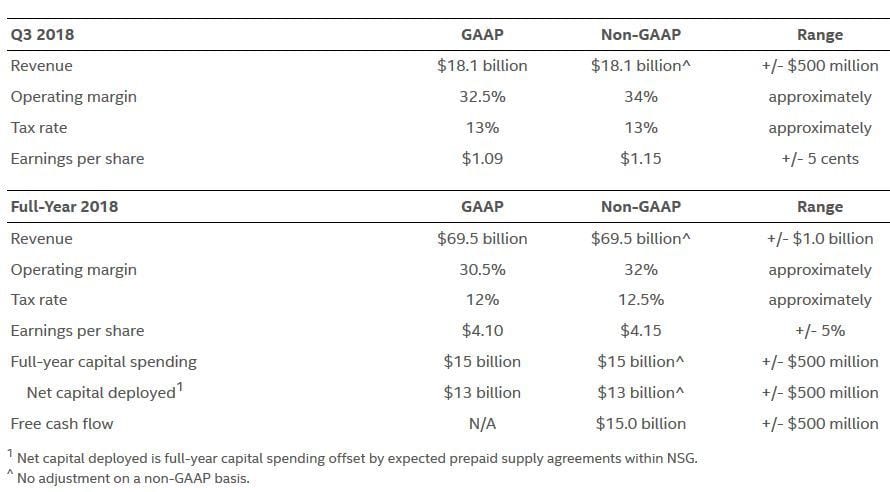
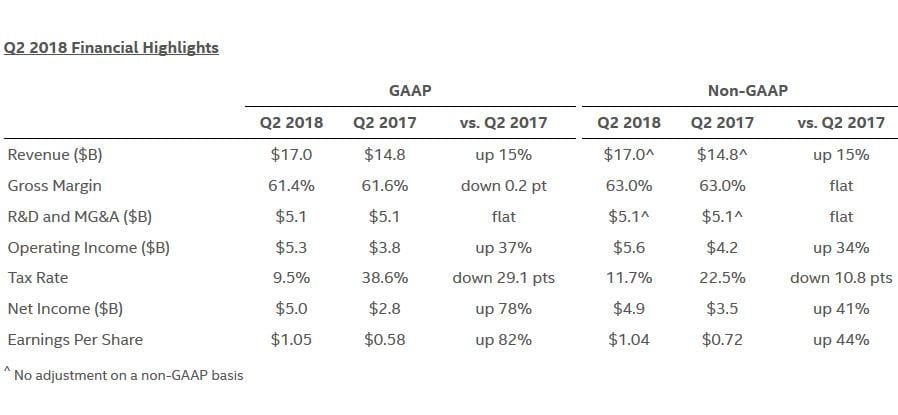
In general, the company's income has risen to $ 5.010 billion, which represents $ 1.05 per share. Thomson Reuters released a forecast of $ 0.96, so the forecast has been greatly improved in this regard. The company continues with good muscle, but the problems with 10nm, it is true that they are beginning to give problems.
Source: TPU


